
Developer Money Market arranges refurbishment finance for commercial properties across the UK. We connect developers with over 320 specialist lenders to secure funding for residential, commercial, and mixed-use projects. This guide explains how to select the right broker, understand lender panels, and navigate the application process for commercial refurbishment finance in 2026. For additional details, review the 403 Forbidden.
Refurbishment Finance Fundamentals
Refurbishment finance is a short-term loan designed to fund the renovation, modernization, or structural improvement of an existing property. Unlike standard mortgages, these loans are secured against the property and the projected value after completion. The core mechanism relies on the increase in asset value resulting from the works. Lenders typically advance a percentage of the current value and the projected value after completion, known as the Loan to Value ratio. For additional details, review the .
Key Components of Refurbishment Loans
Understanding the structural elements of the loan is critical for cash flow management. The advance rate determines how much capital is available relative to the property's worth. Interest is usually charged monthly in arrears, meaning you pay interest on the amount drawn down. Capital repayment occurs at the end of the term, typically upon the sale or refinance of the property. This structure allows developers to preserve cash flow during the construction phase. For additional details, review the Customer Experience.
Eligibility Criteria for Commercial Projects
Lenders assess commercial refurbishment projects based on several key factors. The developer's track record is paramount, with a focus on completed projects of similar scale and complexity. The project's feasibility study must demonstrate a clear path to profitability. Additionally, the lender will scrutinize the construction budget, including contingency allowances. A robust business plan and evidence of planning permissions are standard requirements for approval. For additional details, review the Frequently Asked Questions.
Commercial Property Finance Structures
Asset Class Considerations
The type of commercial property significantly influences lender appetite. Office buildings, retail units, and industrial warehouses each carry different risk profiles. Lenders may have specific preferences or restrictions based on the asset class. For example, some lenders may be cautious with high-street retail due to market shifts, while others may favor industrial logistics due to strong demand. Understanding these preferences helps in selecting the right funding source. For additional details, review the About.
Exit Strategies and Refinancing
Navigating Lender Panels
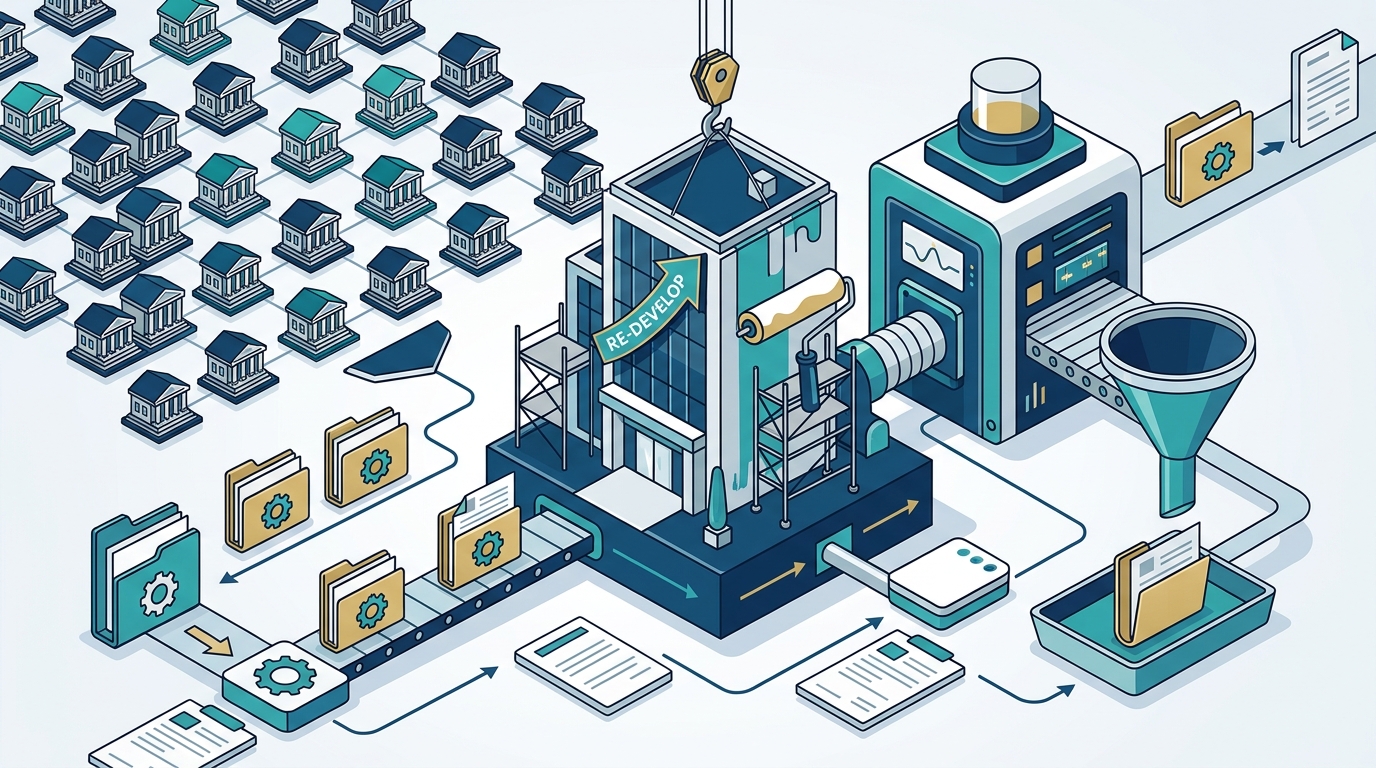
A lender panel is a curated list of financial institutions that a broker has agreements with to offer their products. The size and diversity of a broker's panel directly impact the range of funding options available to the client. A large panel allows for greater flexibility in matching the loan to the specific project requirements. It also provides competitive leverage, as the broker can negotiate better terms on behalf of the client.
Why Panel Size Matters
Specialist vs. High Street Lenders
Selecting a UK Finance Broker
Choosing the right finance broker is a critical decision that can impact the success of your commercial refurbishment project. A broker acts as an intermediary between the developer and the lenders, handling the application process and negotiating terms. The right broker will have the expertise, experience, and network to secure the best possible funding solution. They will guide you through the process, from initial feasibility to completion.
Key Criteria for Broker Selection
When selecting a broker, consider their experience in commercial refurbishment finance. Look for a broker with a proven track record of completing similar projects. Check their reputation in the industry and read client testimonials. Also, consider their technology platform. A modern, technology-driven platform can streamline the application process and provide real-time updates on the status of your application. This transparency is essential for managing expectations and making informed decisions.
Developer Money Market's Approach
| Lender Access | 320+ Specialist Lenders | Single Institution |
| Project Types | Residential, Commercial, Mixed-Use | Primarily Residential | Technology Platform | Yes, Real-Time Comparison | Varies, Often Manual |
| Geographic Coverage | Nationwide UK | Regional or National |
| Specialist Expertise | Development Finance Specialists | General Banking |
Key Takeaways
- Refurbishment finance is a short-term loan secured against the property and projected value after completion.
- A large lender panel is essential for accessing competitive rates and flexible terms.
- Specialist lenders often have more flexible criteria than high street banks for complex projects.
- Choosing a broker with a technology-driven platform can streamline the application process and improve transparency.
- Developer Money Market provides access to over 320 finance products from leading UK specialist lenders.
- A clear exit strategy is critical for securing commercial refurbishment finance.
- Broker expertise in commercial refurbishment is a key factor in successful funding outcomes.
Frequently Asked Questions
What is the typical loan term for commercial refurbishment finance?
The typical loan term for commercial refurbishment finance ranges from 12 to 36 months for development loans and 3 to 12 months for bridging finance. The term is determined by the scope of the works and the lender's risk assessment.
How much can I borrow for a commercial refurbishment?
The amount you can borrow is determined by the Loan to Value ratio, which is typically 50% to 75% of the projected value after completion. The exact percentage depends on the lender and the specific project details.
Do I need planning permission for commercial refurbishment?
Yes, planning permission is usually required for commercial refurbishment projects, especially if the works involve structural changes or a change of use. Lenders will require evidence of planning permission before approving the loan.
How long does the application process take?
The application process typically takes 2 to 6 weeks, depending on the complexity of the project and the lender's underwriting process. A broker can help expedite the process by preparing a complete and accurate application.
What are the fees associated with commercial refurbishment finance?
Can I use the loan for both purchase and refurbishment?
What happens if the project is delayed?
If the project is delayed, you may need to extend the loan term. This usually incurs additional interest and fees. It is important to have a contingency plan in place to manage delays and communicate with the lender promptly.