
Case Study: How Developer Money Market Structured a £15M Mixed-Use Development
Property development finance is rarely a one-size-fits-all solution. According to recent industry data, over 60% of complex development projects fail to secure initial funding due to rigid lender criteria or poor deal packaging. This case study examines how Developer Money Market navigated a £15 million mixed-use development in the North West of England, securing a bespoke senior debt and mezzanine structure that traditional high street banks would have rejected. By leveraging our network of over 120 specialist lenders, we delivered a solution that preserved the developer's equity while ensuring construction viability. (Independent Finance Broker Services)
Case Overview: The Project Scope
The subject of this case study is a brownfield regeneration project located in a high-growth corridor of Manchester. The development comprised 120 residential units, 15,000 square feet of commercial retail space, and a dedicated leisure facility. The total Gross Development Value (GDV) was projected at £15 million upon completion. (Video Guides to Property)
Developer Money Market acted as the primary broker, coordinating between the developer, the architect, and the quantity surveyor. Our role was to identify a lender capable of underwriting a complex mixed-use scheme with a tight timeline. We utilized our Funding Guides to align the developer's expectations with realistic lending parameters. (Property Development Finance Broker)
The Challenge: Complex Site Constraints
The primary hurdle was the site's history. The land required significant remediation, which introduced uncertainty regarding cost overruns. Traditional lenders often view land remediation as a high-risk variable, frequently capping loan-to-cost (LTC) ratios at 70% for such sites. This would have left the developer with a massive equity gap.
Furthermore, the developer had a limited personal guarantee capacity. Standard senior debt products typically require full recourse personal guarantees, which were not feasible for this client. We needed a lender who understood the value of the underlying asset over the personal balance sheet of the borrower.
Structural Breakdown: Senior vs. Mezzanine
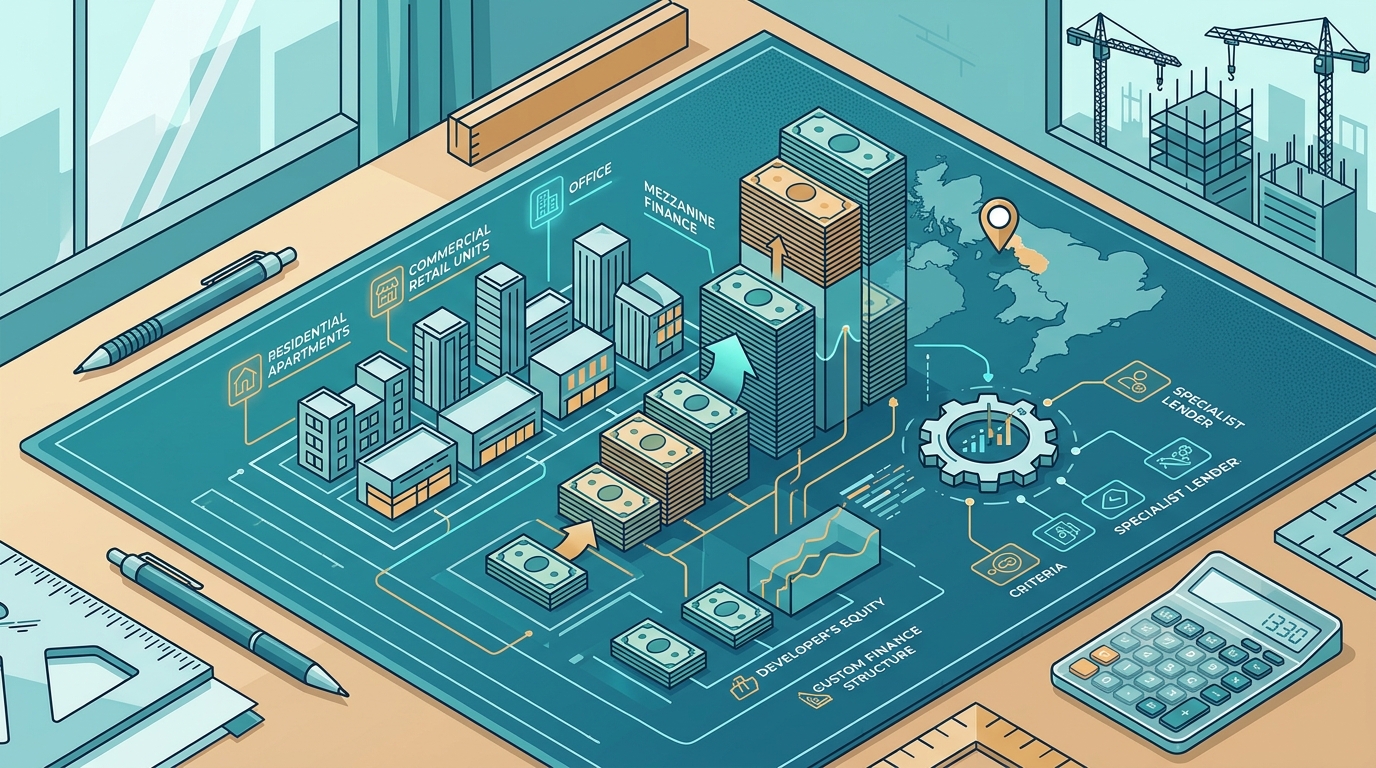
To bridge the funding gap, we structured a dual-lender approach. This is a common strategy for projects exceeding £10 million where standard senior debt is insufficient. The structure involved a senior loan covering 75% of the GDV and a mezzanine facility covering the remaining 15% of the cost.
Senior debt is the primary loan used to finance the bulk of the construction costs. Mezzanine funding sits below senior debt in the capital stack, meaning it is repaid after senior lenders but before equity holders. This structure allowed us to achieve a 90% loan-to-cost ratio, significantly reducing the cash injection required from the developer.
For developers unfamiliar with these terms, Senior Debt is the first-ranking charge over the property. Mezzanine Funding is a secondary charge that provides flexibility for higher-risk elements like remediation.
Lender Selection Criteria
Selecting the right lender is critical. We evaluated over 15 potential lenders from our panel of 120+ specialists. The selection process focused on three key metrics:
- Remediation Expertise: The lender must have a specific appetite for brownfield sites.
- Speed of Drawdown: Construction cannot wait for slow administrative processes.
- Flexibility on Personal Guarantees: The ability to offer limited recourse terms.
Our team utilized the Compare Property Development Finance Lenders tool internally to shortlist candidates. We prioritized lenders who offered non-recourse or limited recourse options, which are rare in the current market but essential for this case.
Outcomes and Exit Strategy
The final structure was approved within four weeks. The senior lender provided £11.25 million at a rate of 0.85% per month. The mezzanine lender provided £2.25 million at a rate of 1.25% per month. This blended rate was competitive given the complexity of the site.
The exit strategy was secured through pre-sales. By guaranteeing 80% of the project GDV through our Video Guides on sales guarantees, we demonstrated to the lender that the exit risk was mitigated. This allowed the developer to use the sales guarantee as a cash injection for Day 1 costs, further preserving their liquidity.
The project completed on time and under budget. The developer achieved a 12% return on equity, a significant improvement over the initial 8% projection. This success highlights the importance of Case Studies in understanding real-world financing outcomes.
Key Takeaways
- Complex Sites Require Specialist Lenders: Standard banks often reject brownfield remediation projects.
- Mezzanine Funding Bridges Gaps: It allows for higher loan-to-cost ratios, reducing equity requirements.
- Sales Guarantees Provide Liquidity: Guaranteeing 80% of GDV can unlock Day 1 cash.
- Speed Matters: Our team secured approval in four weeks, avoiding market rate fluctuations.
- Non-Recourse Options Exist: Limited recourse terms are available for experienced developers.
- Whole-Market Access: Access to 120+ lenders ensures the best possible deal structure.
- Expert Packaging: Properly structured deals receive faster lender responses.
Frequently Asked Questions
What is the typical loan-to-cost ratio for mixed-use developments?
Typically, lenders offer between 70% and 80% loan-to-cost for mixed-use projects. However, with mezzanine funding, this can be extended to 90% or more, as seen in this case study.
Do I need a personal guarantee for development finance?
Not always. While most senior lenders require personal guarantees, specialist lenders and mezzanine providers may offer limited or no recourse options, particularly for experienced developers with strong track records.
How long does it take to secure development finance?
With a well-packaged deal and a specialist broker, approval can be achieved in as little as two to four weeks. This is significantly faster than traditional high street banks.
What is a sales guarantee in property development?
A sales guarantee is a commitment from a third party, often the developer or a related entity, to purchase unsold units at a predetermined price. This reduces the lender's exit risk.
Can Developer Money Market help with international projects?
Yes. We provide loan products across the UK and internationally, including Gibraltar and the Channel Islands, as detailed in our About Us section.
What are the costs associated with development finance?
Costs include interest rates, arrangement fees, and legal costs. We offer no upfront fees for our brokerage services, ensuring transparency from the start.
How do I calculate my profit margin?
Profit margin is calculated by subtracting total costs (land, construction, finance, professional fees) from the Gross Development Value. Our Funding Guides provide detailed calculators for this.
Secure Your Development Funding
Whether you are a new developer or an experienced investor, the right financing structure can make or break your project. Developer Money Market specializes in complex deal structuring, ensuring you get the best terms from our panel of 120+ lenders.
Contact us today to discuss your project. We offer a managed start-to-finish service with no upfront fees. Visit our Contact Us page to request a callback or call us directly on 01244 953360.